
Fintech Integration Services
What is fintech integration?
Fintech integration is the layer that connects a product to the financial systems it needs to run on: payment gateways and rails, core banking and open banking providers, KYC/AML and identity verification vendors, and internal data systems. Lenders, software platforms and retailers use it so data moves between those systems automatically instead of through manual re-entry.
of European consumers abandoned a financial application during onboarding
of the average company’s applications are integrated
Fintech integration services we provide


Loan platform and core banking integration
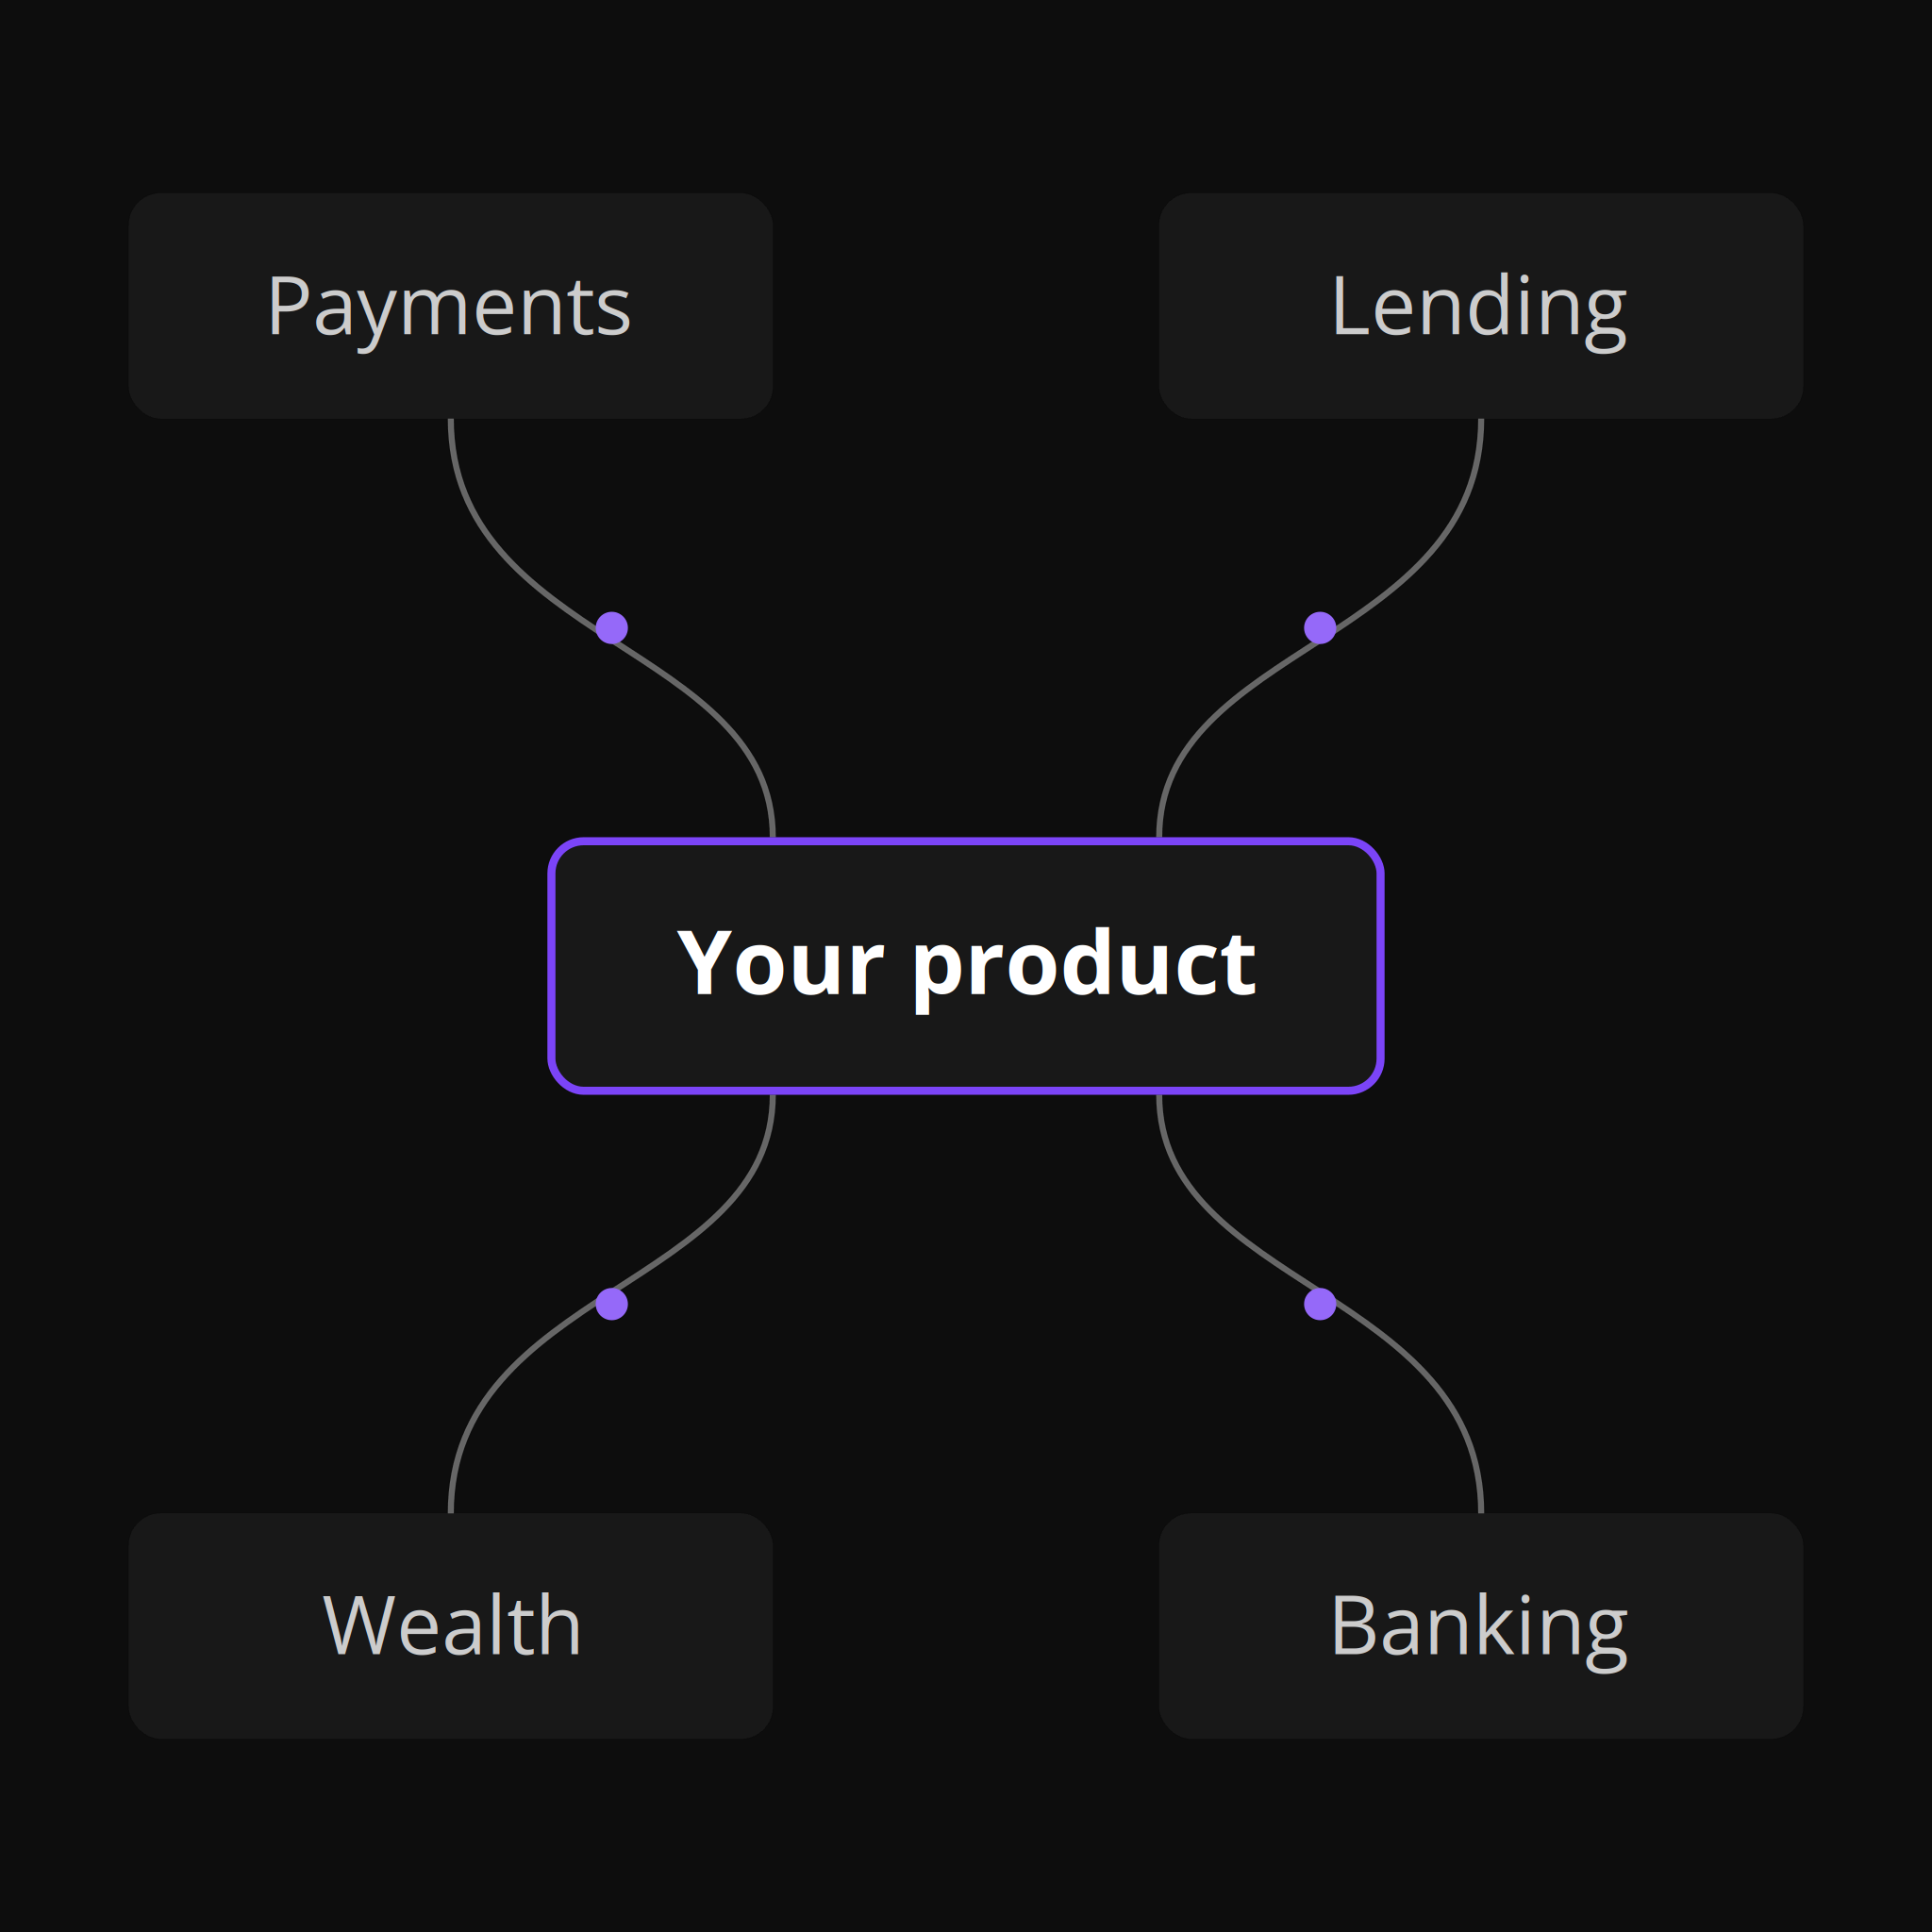
Lenders running origination and servicing on a single legacy vendor hit a ceiling the moment their loan book outgrows it. We design and build the middleware layer that connects best-of-breed platforms, origination on one side, servicing on the other, so data moves between them automatically instead of through manual re-entry.
Identity verification and KYC/AML integration
Fraud has moved past what a simple pass/fail ID check can catch. We connect your platform to identity verification infrastructure via secure API, then layer in custom decisioning so the result is a structured, auditable decision rather than a binary yes or no.
Payment rail and gateway integration
Accepting payments online or in-app means connecting to card processors, gateways, and the rails that move money (ACH, SWIFT, SEPA, or Faster Payments, depending on market). We architect this layer with security and auditability built in from the start, not retrofitted once a compliance review flags it.
Open banking and account data integration
Pulling bank account data with a customer’s consent, or taking payments directly from an account, requires connecting to an open banking layer and handling the compliance obligations that come with it. We build this as part of the same financial-grade architecture we use for core banking and payment work.
Legacy system and data integration
Financial data trapped in manual processes, spreadsheets, or disconnected internal systems is a scaling and compliance problem. We’ve replaced manual document and data workflows for a financial services client with automated, cloud-native systems that pull from multiple internal sources into one place.
Integration consulting and discovery
Before any code is written, we map the systems involved, the compliance requirements, and the real integration points, so the build doesn’t stall on a wrong assumption six weeks in.
Dedicated integration teams
Some integration work needs to sit inside your own engineering team rather than run as a separate vendor project. We embed senior engineers directly into client teams, working inside their architecture governance and their own delivery practices.
Embedded finance integration
Software platforms and retailers want payments, balances or banking inside their own product rather than sending users elsewhere. We build those features into your platform on top of embedded finance providers, so your users get financial services under your brand.
Billing and subscription billing integration
Recurring revenue depends on billing that charges correctly, retries failed payments and presents bills clearly. We integrate billing and bill-presentment systems with your payment stack and your accounting data.
Integration support and maintenance
Integrations don’t stay finished after launch. Providers change their APIs, retire old versions and update compliance rules. We monitor and maintain your integrations once they’re live, so a vendor change doesn’t turn into a broken checkout or a failed KYC check.
Platforms and providers we integrate with
Fintech integration challenges we solve
Fintech integrations, lending, wealth management software we deliver
Payment gateway and virtual card integration
Payment gateway and virtual card integration
34% increase in successful credit-card payments
2× increase in unique users and hotel searches
99.69% lowest weekly platform uptime, up from 97.49%


Custodian data feed integration
Custodian data feed integration
Daily automated sync of positions, cash balances, and market values
Corrected a net-worth calculation that had been excluding cash, improving accuracy across all accounts
40%+ in development costs saved through AI-native delivery

Investment platform and transaction system sync
Investment platform and transaction system sync
£12.9B in assets managed through the platform
63,000+ investor profiles managed end-to-end
750+ employees using the platform for day-to-day operations

Privacy-first identity verification and credential onboarding
Privacy-first identity verification and credential onboarding
100% PII protection, with verification data deleted immediately after processing
18+ microservices migrated from Amazon SQS to Kafka
3 OCR providers evaluated with a Golang proof of concept

Document and bank credential verification hub
Document and bank credential verification hub
Adopted by the US and Canadian governments, the Canadian interbank network, and financial institutions
Document verification service developed in 7 months
30+ developers delivering under tight deadlines

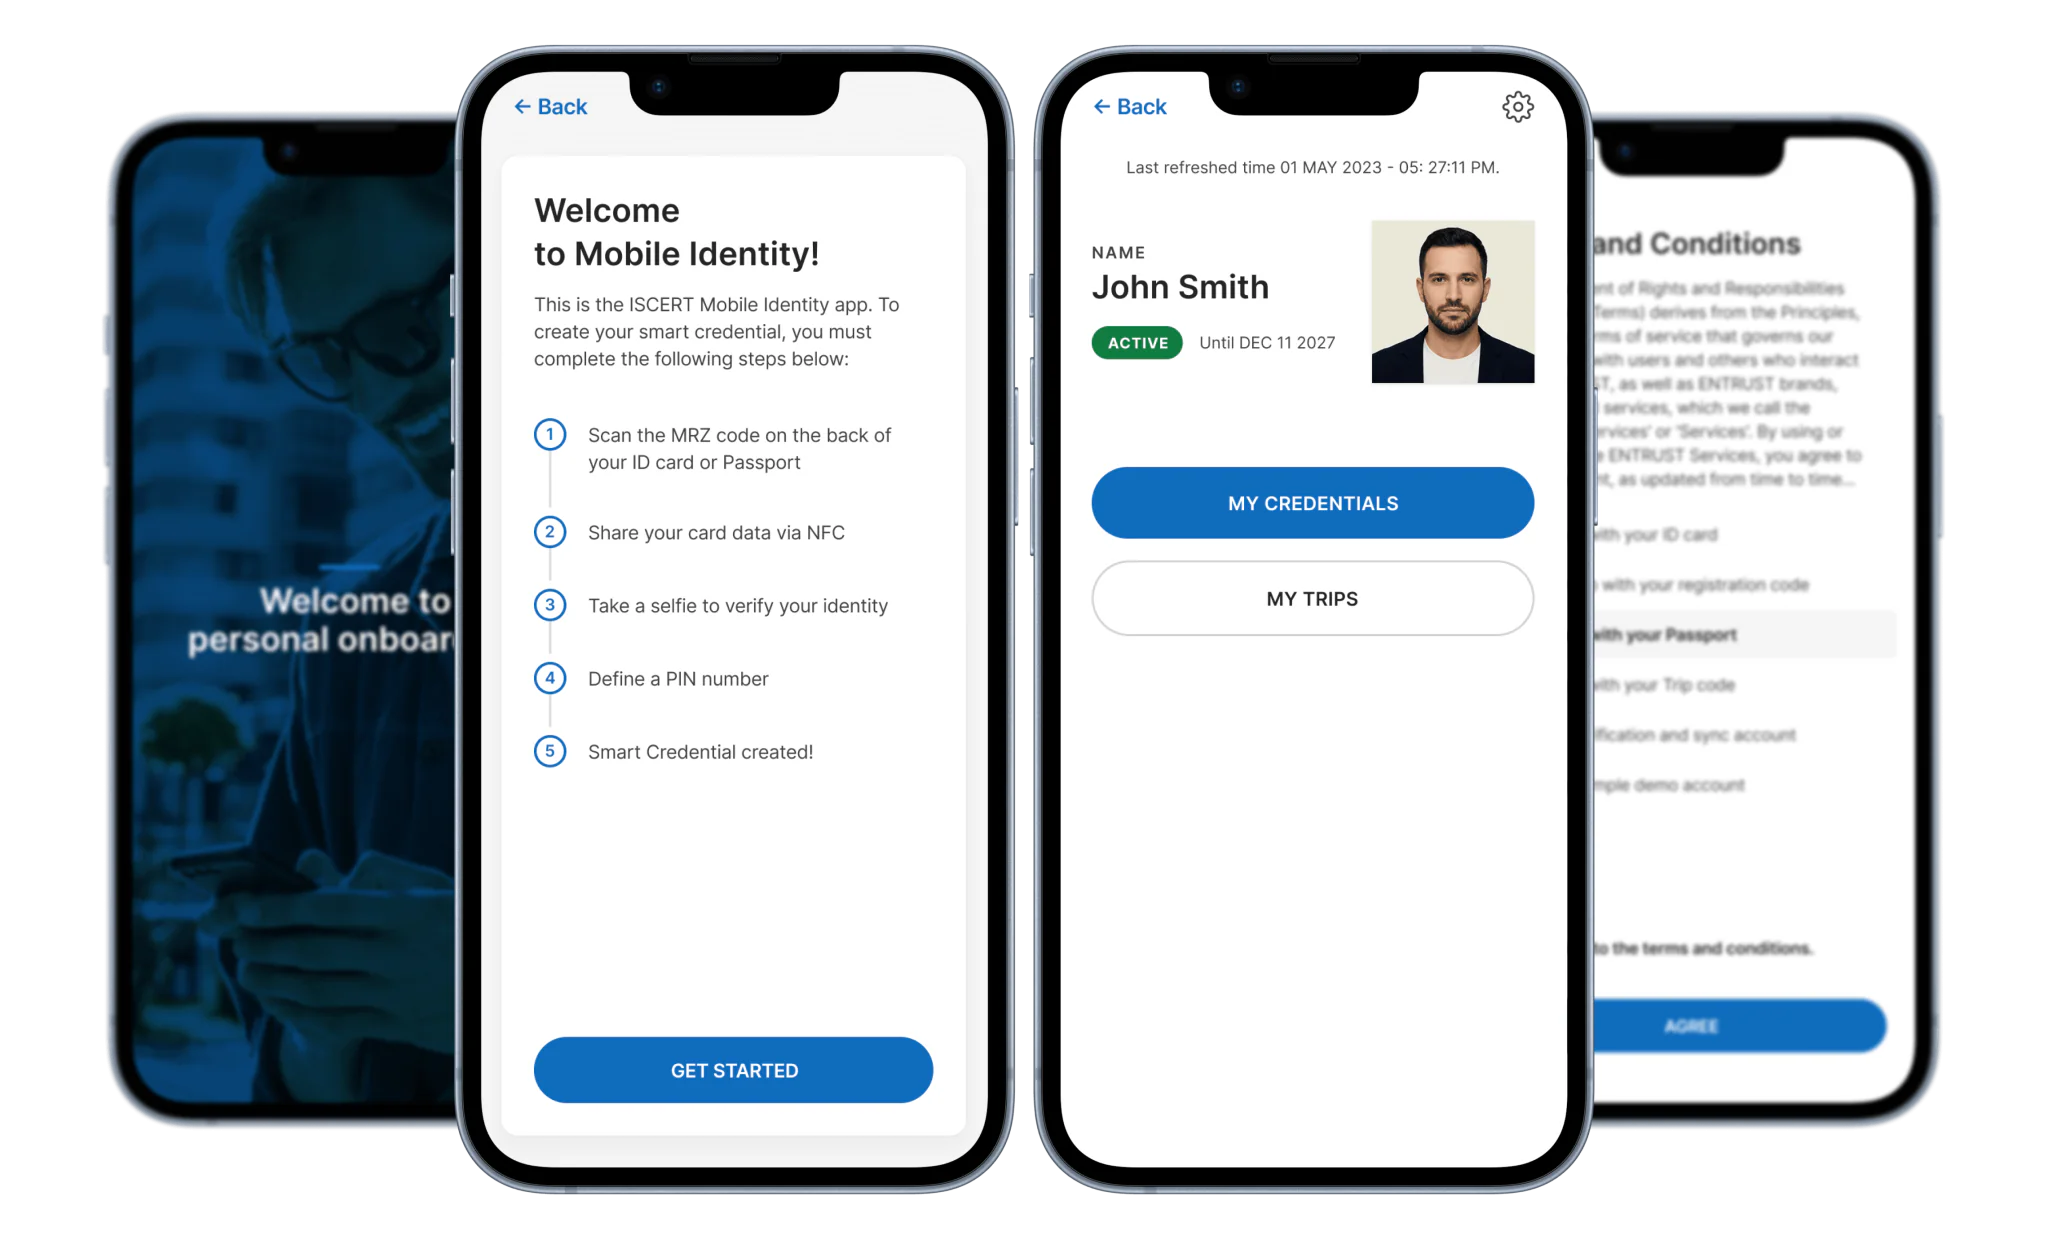
Verifiable digital credentials
Verifiable digital credentials
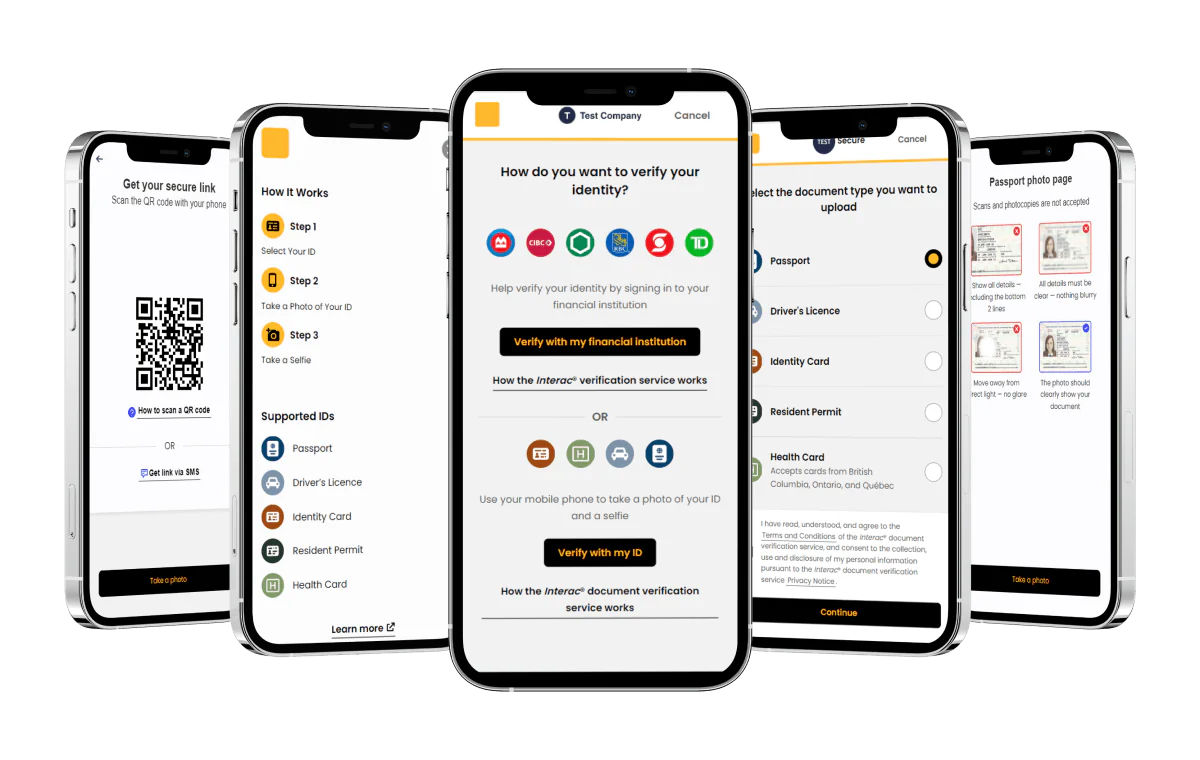
Digital identity verification platform used by the Government of Canada
Compliant with W3C standards
Instant identity verification using digital versions of passports, licences, and birth certificates
Real-time KYC integration
Real-time KYC integration
2,500+ document types now supported across jurisdictions
6 months the integration build ran alongside live platform development, with zero downtime
2 years of ongoing development partnership since the initial integration
Loan origination and servicing integration
Loan origination and servicing integration
20+ end-to-end loan flows automated across origination and servicing
100% of planned legacy-parity features shipped on schedule, validated against real migrated loan data


Fintech integration pricing
Integration Proof of Concept
Single integration
Integration layer
Hire Fintech developers

Why choose Euristiq for fintech integration projects
Why Euristiq for fintech integrations
Euristiq has spent 10+ years building and integrating financial software for digital lenders, neobanks, asset managers, and non-financial companies embedding financial services, across payments, lending, wealth management, digital banking, RegTech, and embedded finance/BaaS.

Compliance as a day-one decision
- PCI DSS, SOC 2 and GDPR
- PSD2/Open Banking and DORA
- AML/KYC requirements
Results in production
- Corpay: 34% more successful card payments, uptime raised from 97.49% to 99.69%
- Gen Digital (Norton): 18+ microservices moved from Amazon SQS to Kafka with 100% PII protection
- Octopus Group: manual reconciliation eliminated across £12.9 billion in assets
- Mozaiik Wealth Tech: MVP to multi-tenant SaaS in months, with over 40% saved in development costs
How we deliver
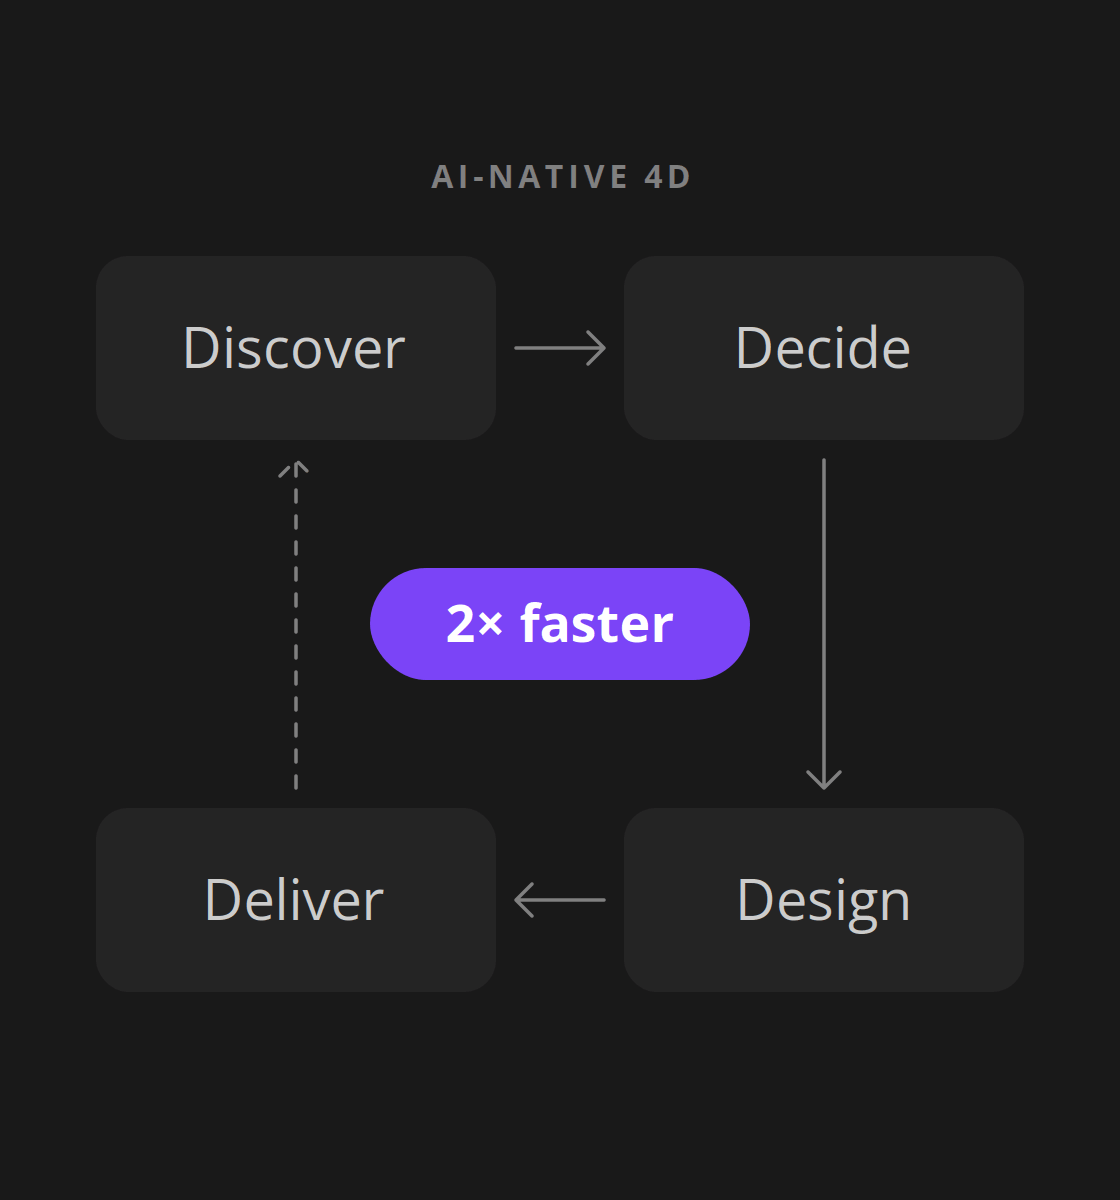
- AI-native 4D approach: Discover, Decide, Design, Deliver
- Custom fintech software delivered 2× faster than traditional development
- AWS Advanced Tier Services Partner with three AWS
- Competencies
ISO/IEC 27001:2022 certified
Fintech integrations for lenders, identity platforms and investment firms
Integrations for lenders
Euristiq connects loan origination platforms to core banking and servicing systems, so lenders moving off a single-vendor legacy platform keep both sides in sync without manual re-entry.
Integrations for digital identity and fintech platforms
Euristiq integrates identity verification vendors into fintech products and adds custom fraud decisioning, so each check returns a structured, auditable result without pausing your product roadmap.
Integrations for investment and financial services firms
Euristiq replaces manual data handling with automated integrations that pull from multiple internal systems into one place, with security and access control built in from the start.
Which integration approach fits your product?
Our tech stack


FAQ
Can an integration run without disrupting our live product?
Yes. Our identity verification integration for a digital identity platform ran for six months alongside live platform development with zero downtime, and our loan origination integration shipped full legacy parity on schedule.
What compliance standards do you build integrations around?
What compliance standards do you build integrations around?
We design integrations around the compliance requirements each client needs to meet, including PCI DSS, PSD2/open banking, GDPR, and relevant KYC/AML obligations. We build software designed to meet these requirements; the client remains responsible for its own compliance status.
Do you integrate with platforms you haven’t worked with before?
Yes. Our approach starts with discovery and architecture design regardless of the specific platform, and we’ve connected systems like loan origination and core banking platforms, and identity verification vendors, that don’t integrate natively.
Should we build a custom integration or extend an existing platform?
It depends on whether your provider stack is standard or whether your systems need custom orchestration between platforms that don’t integrate natively. We can advise after a discovery phase, which is the first stage of any integration project.
Do you provide a dedicated team for ongoing integration work?
Yes. We offer team extension, where our engineers work embedded inside your existing engineering team, and we’ve maintained ongoing integration partnerships for multiple years on single accounts.
Should we connect to banks through an aggregator like Plaid or directly?
An aggregator such as Plaid, TrueLayer or Tink gives you one API that reaches thousands of banks, so you launch fast, and the aggregator usually holds the open banking licence. You pay fees per connection or API call. A direct bank connection means a separate build for each bank’s own API, so launch is slower and you maintain every connection. You avoid middleman fees, but you may need your own licence and certificates. An aggregator suits products that need broad bank coverage quickly. Direct connections suit high volumes with a few banks, or corporate host-to-host payments.
How do you keep PCI DSS scope small?
The fewer of your systems that touch raw card data, the smaller your PCI DSS scope. We use the provider’s hosted fields or hosted payment pages so card details go straight to the provider, and tokenization so your systems store tokens instead of card numbers. Credentials and tokens are managed securely across providers, and compliance is part of the architecture from the start, not added after a review.
Can you switch us to a new payment provider without downtime?
Yes. We put an integration layer between your product and the providers, so a new provider can be connected without rebuilding your product. The old and new providers run in parallel, traffic moves over in phases, and fallback to the old provider stays in place until the switch is complete. Stored card tokens usually need a migration coordinated between the two providers, and we plan that as part of the move.
Who maintains the integration when a vendor changes its API?
We can, through our integration support and maintenance service. It covers vendor API upgrades and deprecations, monitoring and incident fixes, and updates for changing compliance rules. If your own team takes over, they get documentation and Architecture Decision Records for every major integration choice, so they can maintain it without us.
Build or buy: should we build our own payment gateway?
For most companies, no. Building a gateway means PCI DSS Level 1 compliance, relationships with acquiring banks and ongoing certification work. That only pays off at very high transaction volumes, or if payments are your core product. The usual better choice is to integrate an existing gateway, or several through one integration layer, and build custom logic around it. We recommend build or extend during discovery, based on your volumes and platform stack.
Who owns the code and IP? Do you sign an NDA?
You own the code and intellectual property we create for your project. We sign an NDA before discovery starts, so you can share system details, architecture and compliance documents from the first conversation.

Let’s talk!

